
By Matthias Trüstedt
Group Head of Global P&C

Liability and Safety: The Keys to Autonomous Mobility
Alphabet’s Waymo is doing everything it can to launch its ride-hailing service in London this year. Local manufacturers such as Mercedes-Benz and VW are also pushing ahead with pilot projects: Both autonomous driving and driver-assistance technologies are changing the way we get around.
McKinsey predicts that by 2030, fleets of driverless robotaxis will be on the roads in many countries. However, we will remain in a phase of mixed traffic for some time yet, in which both human drivers and autonomous systems share the roads. As with conventional cars, accidents can occur with autonomous vehicles for various reasons—albeit increasingly rarely due to human error. Wear and tear and hail damage will continue to be issues. At the same time, new risks are emerging, such as when a front-facing camera misclassifies a pedestrian and thus fails to detect them.
But who bears responsibility if the driver cannot be held liable for the accident? Does the liability system need to be rethought—shifting away from the vehicle owner and toward the manufacturer? The answer is clear: No. The proven combination of strict liability and mandatory insurance, as applied in Germany and, in its basic form, across much of Europe and even in China, is the only viable solution from the perspective of victim protection.
Liability for Accidents in an Autonomous World
After all, victim protection must remain the central focus even in accidents involving autonomous vehicles, and responsibilities must be clearly defined in the event of damage. Liability should be simply regulated, regardless of whether a human driver or an autonomous system caused the accident. The system of strict liability ensures this accountability: The owner is liable both for human errors during driving or maintenance and for technical faults—where brake failure is now joined by potential errors in the operating system.
The accident victim should not have to prove a claim against the responsible manufacturer but should instead be compensated straightforwardly by the owner’s auto liability insurer. Under the strict liability system, it is sufficient to prove that the damage occurred during the operation of a vehicle, without having to address product liability issues. The insurer remains the point of contact for the vehicle owner and also assumes any potential recourse, for example against the (software) manufacturer.
In 2017 and 2021, the German legislature amended the legal framework for highly automated, fully automated, and autonomous vehicles. In doing so, the system of strict liability was retained, and only the liability limits were adjusted to meet the requirements of new technologies. After all, one thing remains unchanged: accidents will continue to have multiple causes. The existing system of strict liability therefore provides a proven and flexible foundation for ensuring a clear and fair legal framework, particularly for accident victims.
Data and Standards: The Foundation for Safe Autonomous Mobility
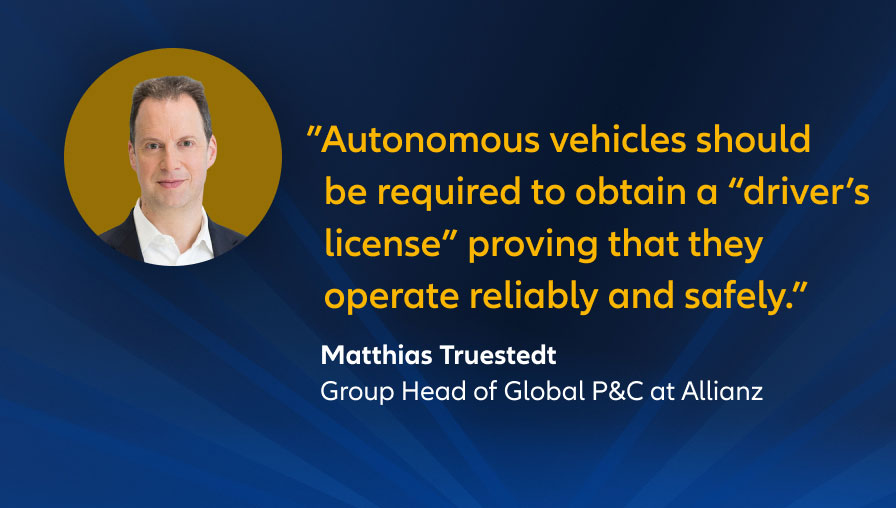
Data is the key to resolving accidents with the necessary reliability and through the familiar routine of insurance claims. With the increasing automation of mobility, only data makes it possible to determine the causes of accidents, assess damages, and thereby improve traffic safety. Therefore, all accidents occurring in autonomous mode should be recorded in a Europe-wide database—jointly operated by manufacturers, regulatory authorities, and insurers. Binding safety standards are equally important. Just as a person must demonstrate their driving skills in a test, an autonomous vehicle should also be required to obtain a “driver’s license” proving that it operates reliably and safely.
Clear licensing standards and certification processes create transparency, comparability, and trust in autonomous mobility. This trust is crucial for societal acceptance. As a result, accident rates will also decline—with positive effects on insurance premiums. This helps keep auto insurance affordable, despite rising repair costs due to complex technology.
When new standards, data availability, victim protection, and insurance coverage all work together, trust in autonomous mobility will grow. And Waymo & Co. will shape the streetscape faster than expected.
Further information
More news
About Allianz
Last updated: September 23, 2026
The Allianz Group is one of the world’s leading insurers and asset managers, active in almost 70 countries and serving around 97 million private and corporate customers*. Our customers benefit from a broad range of personal and corporate insurance services, including property, life and health insurance, as well as assistance services, credit and global business insurance. Recognized for the seventh consecutive year as the number one global insurance brand in Interbrand’s Best Global Brands 2025 ranking, Allianz’s success is built on technology-enabled customer centricity – providing peace of mind, protection, and prevention for our customers and strengthening the resilience of individuals, communities, and societies. We are one of the world’s largest investors, managing around 791 billion euros** on behalf of our insurance customers. Furthermore, our asset managers PIMCO and Allianz Global Investors manage about 2.2 trillion euros** of third-party assets. Thanks to our systematic integration of environmental and social criteria in our business processes and investment decisions, Allianz received an MSCI ESG Rating of AAA (as of March 2026). In 2025, our 156,000 dedicated employees achieved a total business volume of 186.9 billion euros and an operating profit of 17.4 billion euros for our shareholders.
* As of December 31, 2025. Customer count reflects Allianz customers in consolidated entities that are part of the customer reporting scope only.
** As of June 30, 2026.
Cautionary note regarding forward-looking statements
As with all content published on this site, these statements are subject to our cautionary note regarding forward-looking statements: